AITA for Making My Son Repay His $50K Loan?

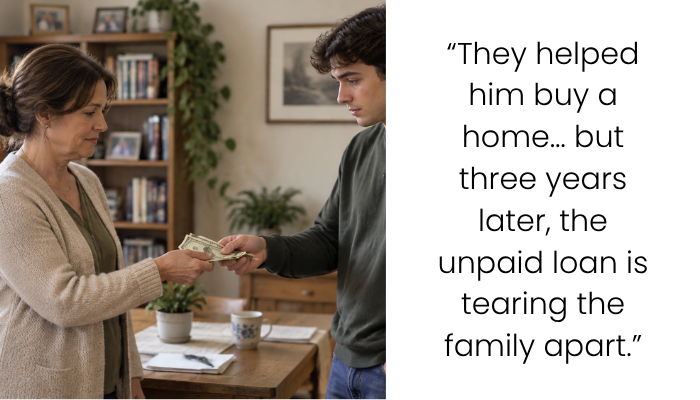
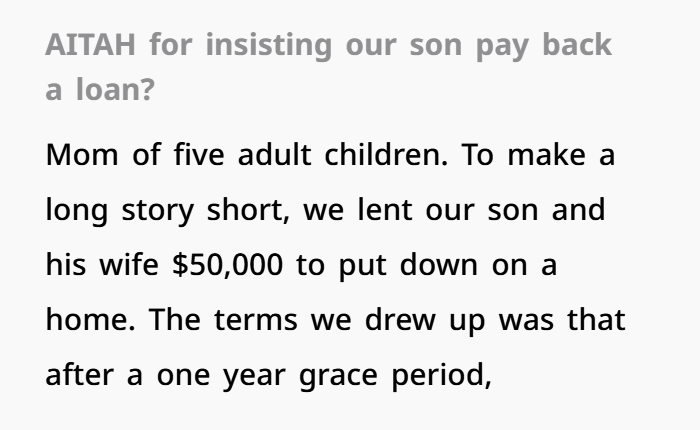
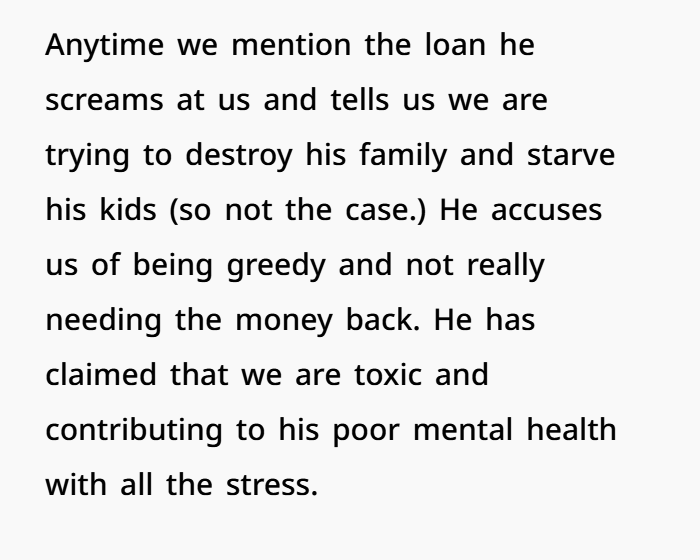
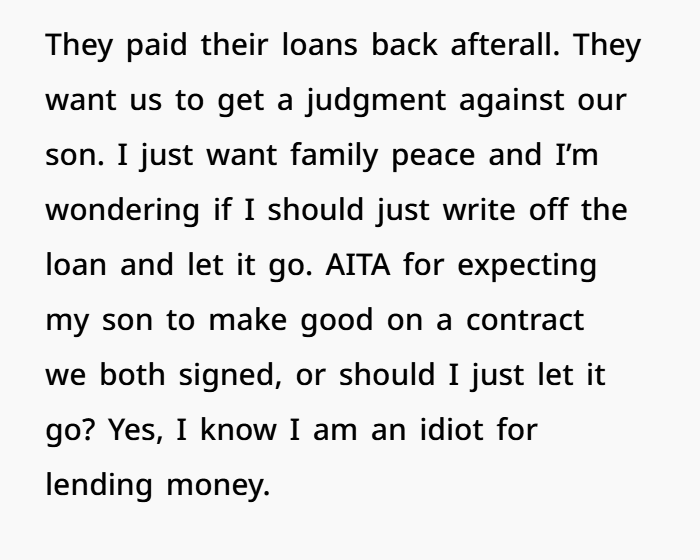
A family money disagreement has caused tension between a mother and her adult son. The mother and her husband loaned their son and daughter-in-law $50,000 to help them buy a house. They created a written repayment agreement to make the loan terms clear for everyone.
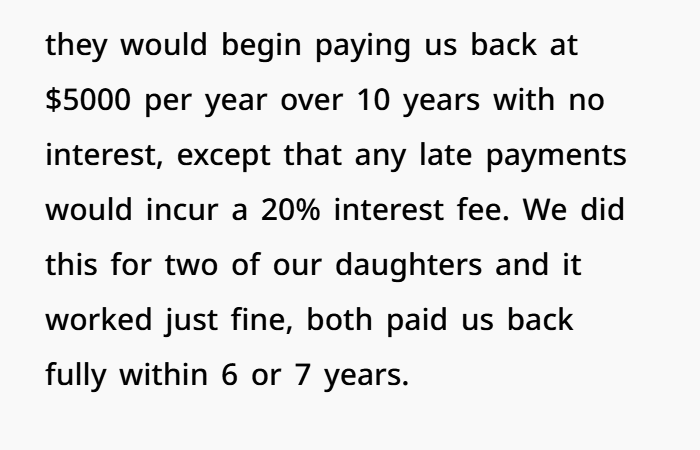
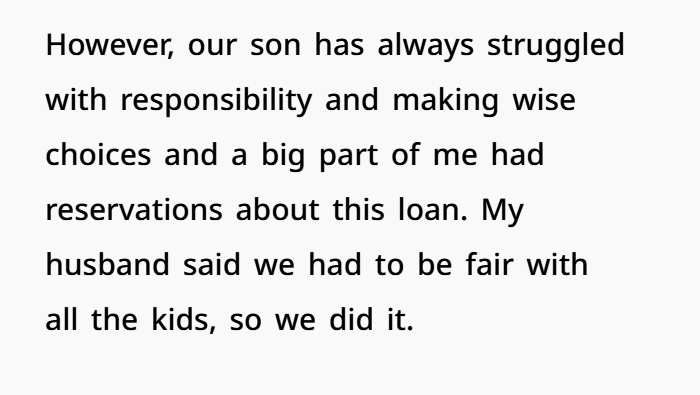
The parents had used the same approach when helping two of their daughters, and those loans were repaid successfully. With their son, things became more complicated when he missed payments and did not follow the agreed repayment schedule.
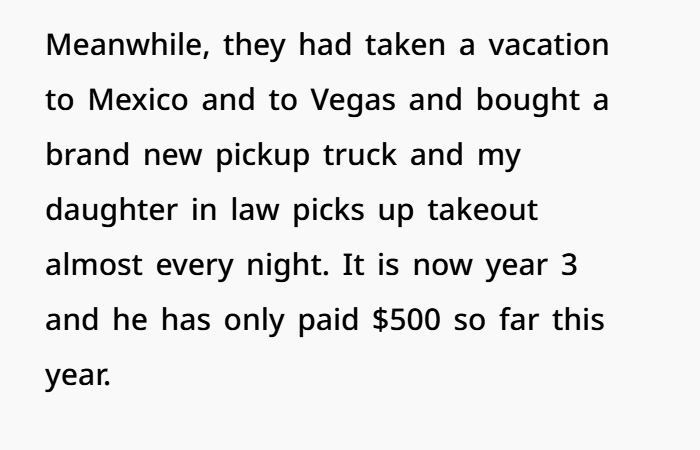
The parents became concerned when they saw their son spending money on personal expenses, including trips, a new truck, and eating out often. They felt confused because he said he could not afford to repay the family loan.
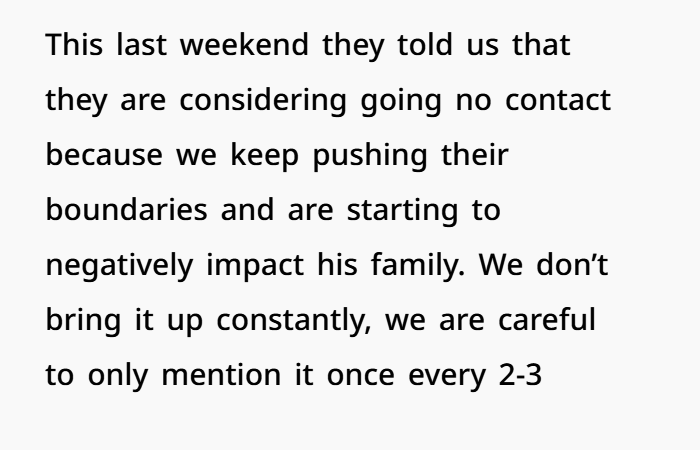
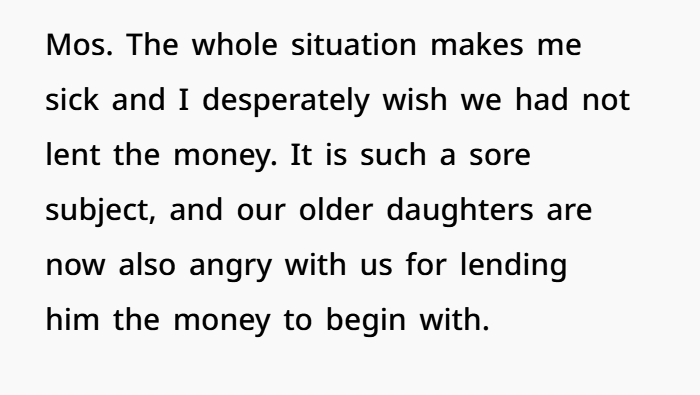
The disagreement has now divided the family. Some relatives want the parents to use legal options, while the mother is thinking about whether forgiving the debt could help repair family relationships and reduce conflict.
When a Family Loan Becomes a Family Problem
Money can be one of the most difficult topics to discuss with family members. A loan between parents and children may start with good intentions, but problems can happen when repayment becomes difficult.
A $50,000 family loan may look like a simple agreement. One person needs financial help, and another person wants to provide support. But when emotions, expectations, and personal relationships become involved, the situation can become much harder.
Family money problems are rarely only about money. They are often about trust, responsibility, and communication.
In this situation, the parents did not simply give money to their son without any expectations. They created a written family loan agreement and allowed one year before repayment began. They also continued helping by providing groceries, baby supplies, and other necessities.
The parents saw this as a way to support their son while also creating a fair financial plan.
However, family loans can become complicated because people may have different ideas about what the money means. The person lending the money may see it as a formal loan. The person receiving it may see it as family support that can be changed when life becomes difficult.
When expectations are not clear, hurt feelings and frustration can grow.
Why a Family Loan Agreement Matters
When lending a large amount of money to a relative, many financial experts recommend creating a written agreement.
A family loan agreement helps both sides understand the rules. It explains important details like repayment dates, payment amounts, and responsibilities.
A basic family loan agreement may include:
- The total amount borrowed
- Monthly payment details
- Repayment timeline
- Interest information, if required
- Late payment rules
- What happens if payments are missed
- Signatures from both people
A written agreement does not mean there is no trust between family members. In many cases, it actually protects the relationship by preventing confusion.
Without clear terms, family members may avoid talking about money because they feel uncomfortable. Over time, small problems can become bigger financial and emotional issues.
Helping Family Members Without Creating More Problems
Many parents want to help their children when they face financial challenges. Supporting a family member during a difficult time can be a caring and generous choice.
However, there is an important difference between helping and enabling.
Helping means providing support while encouraging the person to take steps toward solving the problem.
For example, helping someone create a budget, manage debt, or plan their expenses can improve their financial situation.
Enabling happens when someone continues receiving financial support but does not take responsibility for their own choices.
This does not mean every person who struggles with money is irresponsible. Job loss, unexpected bills, health costs, and family responsibilities can create real financial pressure.
The important thing is having a plan for money management and working toward a solution.
Why Family Debt Can Create Emotional Stress
Many family arguments about debt are not only about unpaid money.
They are often connected to feelings such as:
- Stress
- Disappointment
- Embarrassment
- Anger
- Guilt
- Feeling unappreciated
A person who cannot make payments may feel pressure or shame. Sometimes this can lead to avoiding conversations about money.
At the same time, the person who provided the loan may feel hurt because they believe they tried to help and their kindness was not respected.
This is why honest communication is an important part of personal finance.
Talking about money early can help families avoid bigger problems later.
Understanding the Legal Side of Family Loans
A signed loan agreement can help show that money was borrowed and was not simply a gift.
The legal options available for unpaid family debt depend on local laws and the details of the agreement. In some situations, a lender may be able to take legal steps to recover the money.
However, legal action against a family member is a serious decision.
Before moving forward, families may want to consider:
- Whether the borrower can realistically repay the money
- Whether the loan agreement follows local legal requirements
- Whether both sides can find a solution through discussion
- Whether professional financial or legal advice may help
Some families choose mediation instead of going directly to court. A neutral person can help family members discuss the problem and find a possible solution.
The Emotional Side of Lending Money to Family
For parents, family debt can be especially painful.
A parent may feel caught between two choices. They may want their child to repay the money, but they may also worry about damaging the relationship.
On the other hand, forgiving the debt may create feelings of sadness or disappointment.
Many parents naturally want to protect their children. But adult children also need to learn financial responsibility and understand the importance of keeping agreements.
A parent can care deeply about their child while still expecting accountability.
Financial struggles can happen to anyone. Having money problems does not make someone a bad person. However, dealing with financial challenges requires honesty, communication, and a willingness to find solutions.
Important Money Lessons From Family Loans
This situation shows why financial boundaries are important.
Before lending a large amount of money to a family member, consider these questions:
- Can I afford to lose this money if it is not repaid?
- Will this loan affect my relationship with this person?
- Does this person have a realistic repayment plan?
- Would I make the same financial decision with someone who was not family?
A smart personal finance rule is to only lend money that you can financially and emotionally handle losing.
Clear boundaries do not mean you do not love or support someone. In many cases, good boundaries help protect relationships.
How Families Can Move Forward
A family loan problem can create stress, but it does not always have to destroy a relationship.
Moving forward may require honest conversations, better money management, and realistic expectations from everyone involved.
Some families may benefit from speaking with a financial advisor, debt management professional, or mediator.
The goal is not only to solve the money problem. It is also to rebuild trust and create a healthier way of handling finances.
Family and money can be difficult to balance. But with clear agreements, responsible financial planning, and open communication, many money conflicts can be avoided.
See The Comments Below